Independent feasibility studies for the loan decision.
Lender-engaged studies for SBA 504, SBA 7(a), USDA B&I and conventional loan files in Georgia and the Southeast.
Test whether the proposed site, operating plan and financing can work together. Your credit team receives one finding at the front of the report, backed by five feasibility tests, with the assumptions and limits stated beside it.
The finding comes first
Feasible
The evidence supports the project as proposed, subject to the report's stated assumptions and conditions.
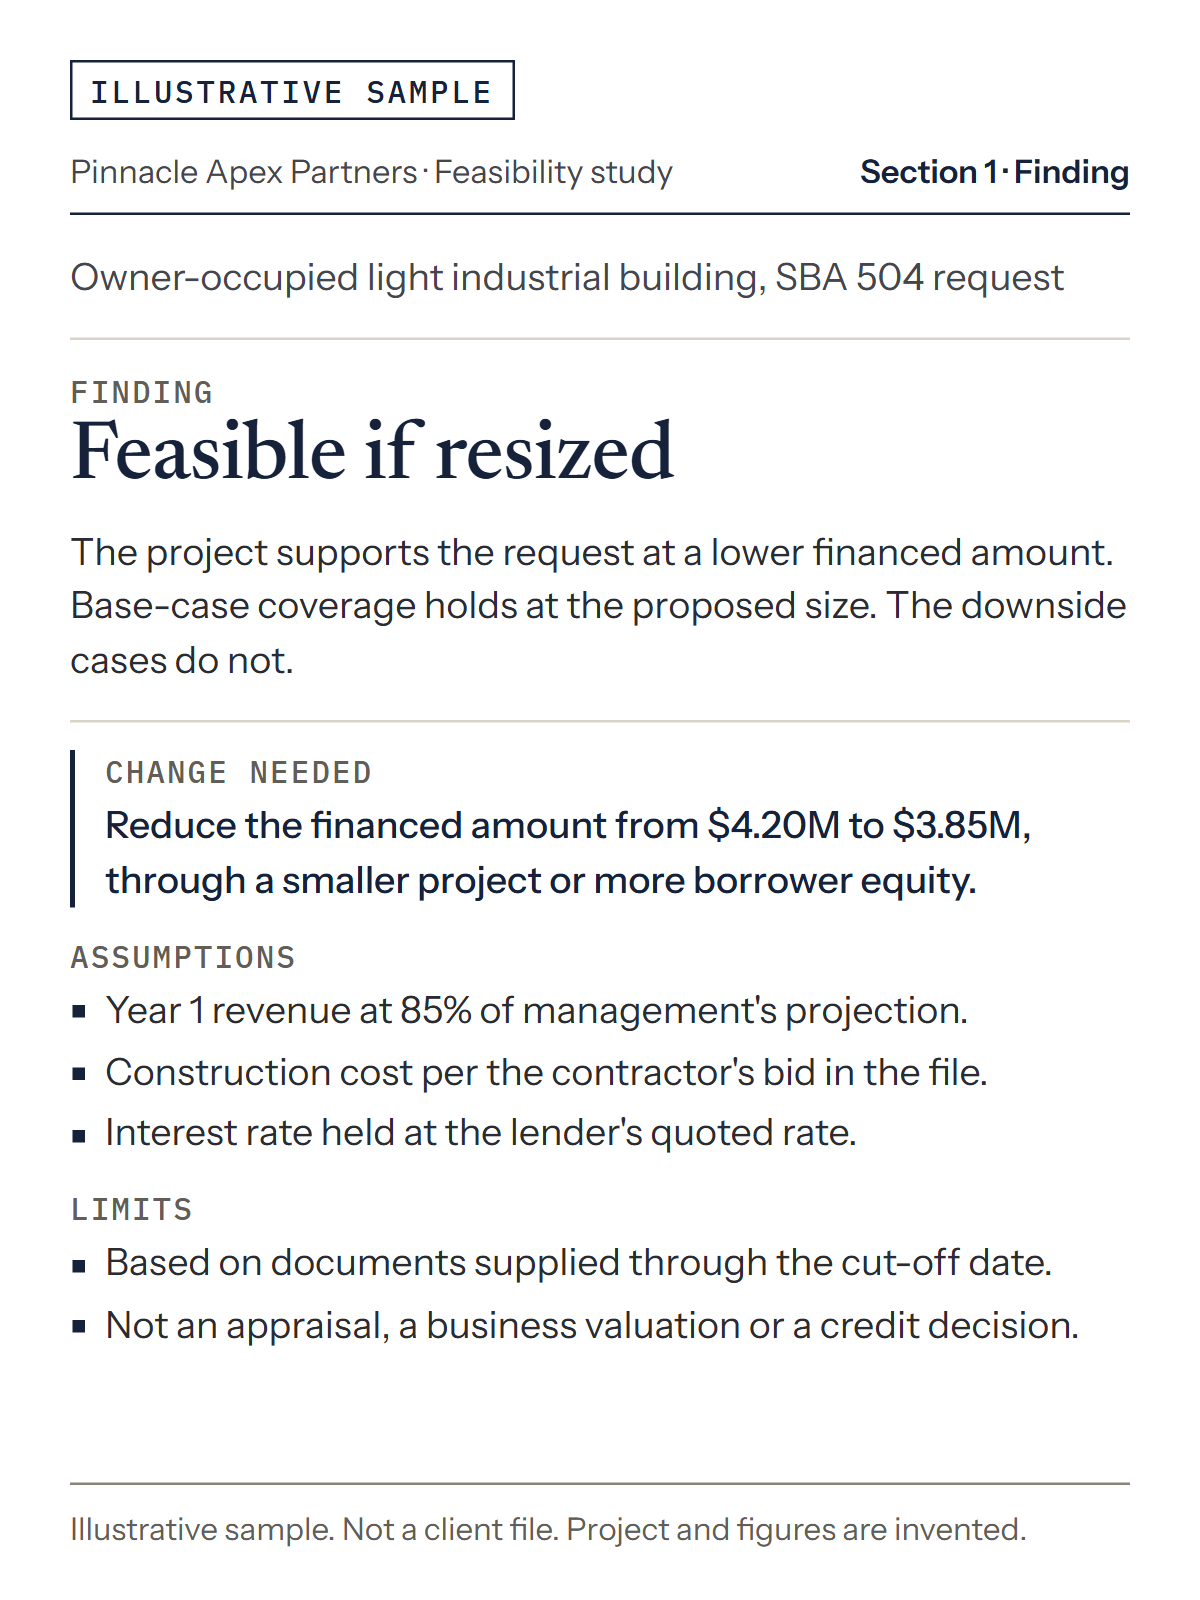
Feasible if resized
The report identifies the change needed, such as a smaller project, a different purchase price, more borrower equity or a lower loan amount.
Not feasible as proposed
The evidence doesn't support the proposed project. The report explains which assumptions fail and why.
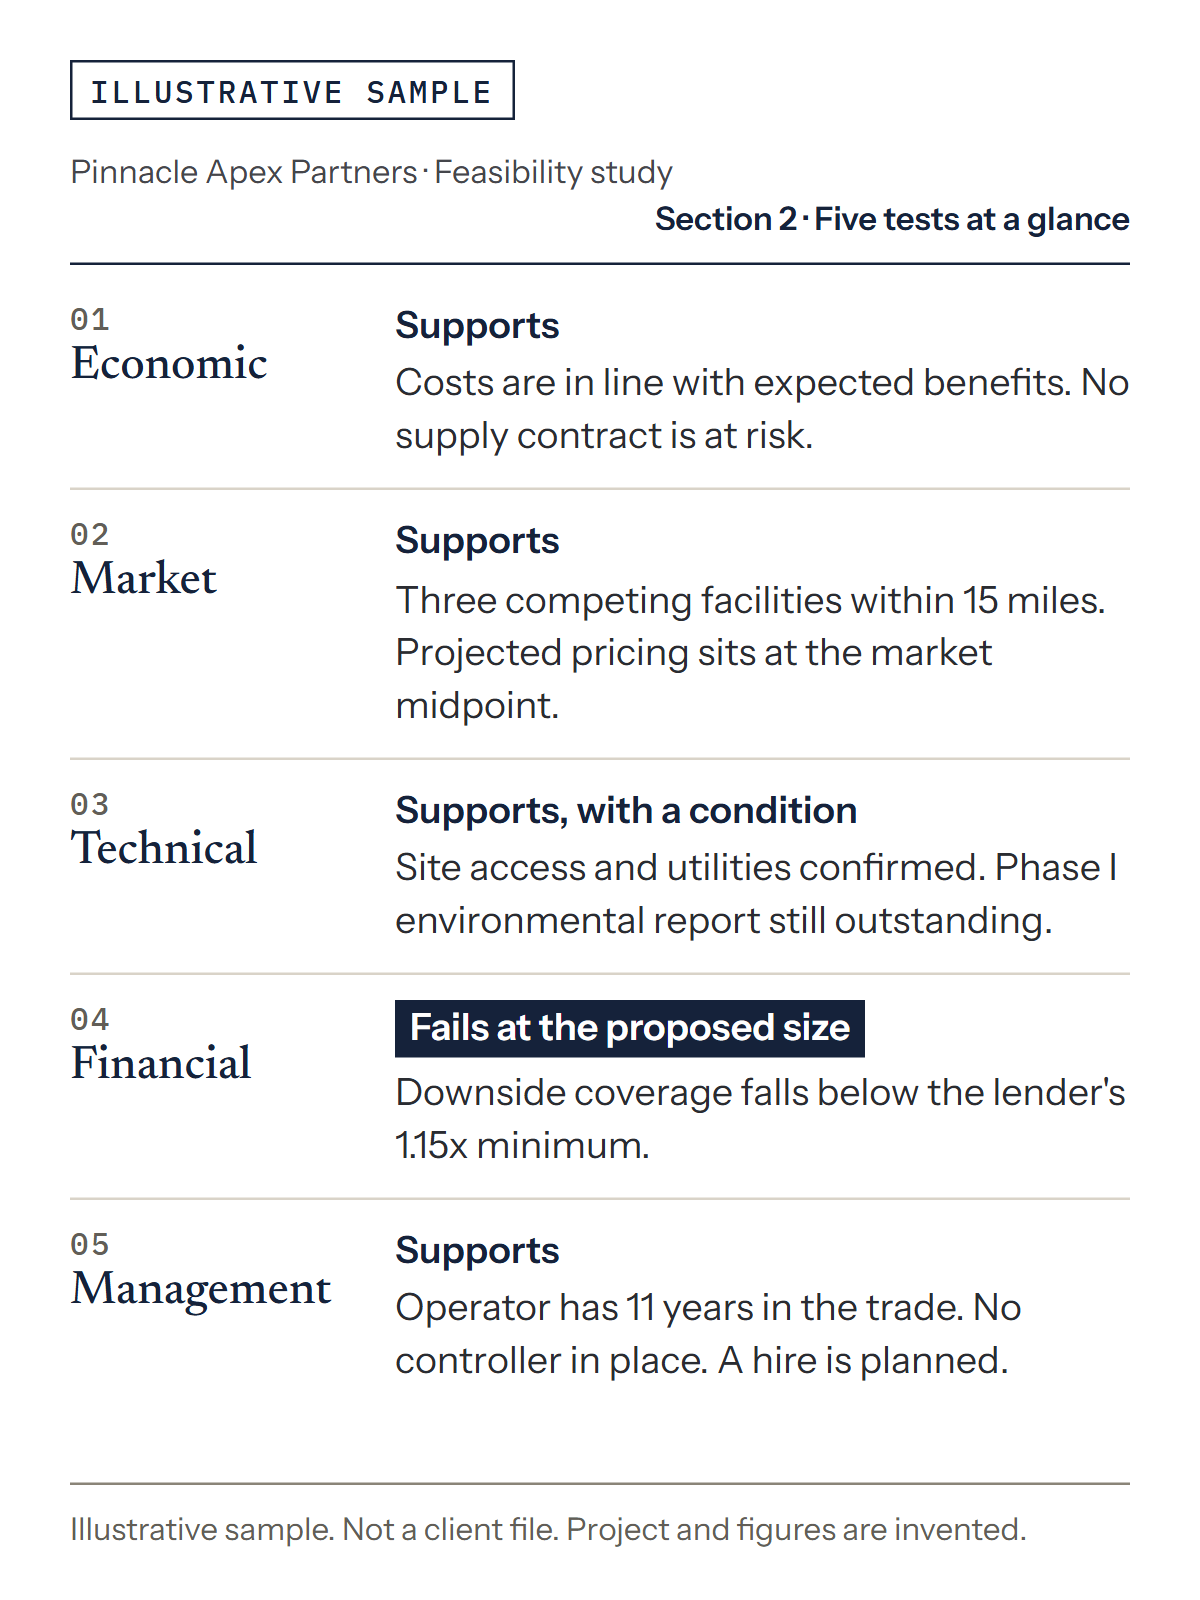
Five tests behind the finding
For USDA B&I files, the scope addresses the applicable components in 7 CFR Part 5001, Appendix A to Subpart D. We confirm the required analysis and preparer acceptability with the lender and agency before engagement.
01 Economic
Compare project costs with expected benefits. Assess essential inputs, supply contracts, environmental risks and the project's effect on the local economy.
02 Market
Test demand against existing and planned supply. Examine the customer base, competing facilities, achievable pricing and the assumptions behind projected sales.
03 Technical
Review the site and operating plan, including access, technology, materials, labor and construction risk. Identify specialist reports and approvals the lender needs.
04 Financial
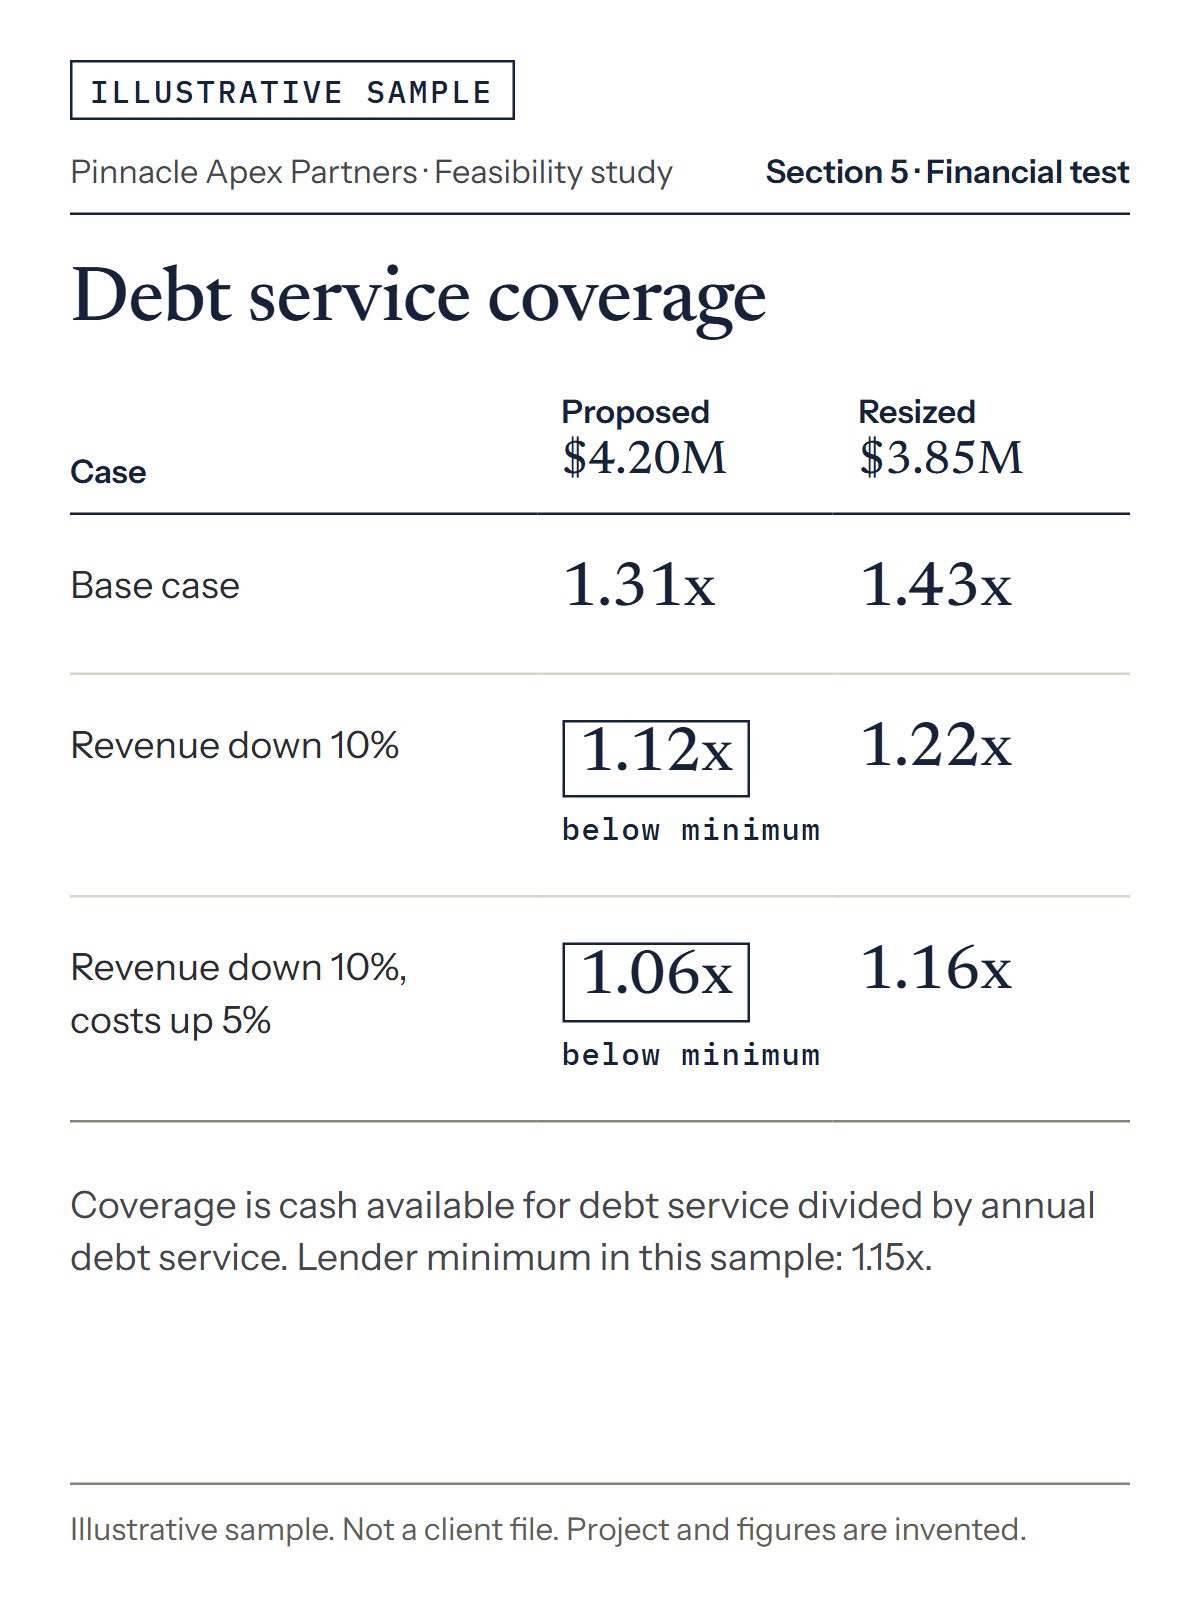
Test projected cash flow and repayment capacity. Review borrower equity, working capital and debt service coverage, then show how the result changes under downside assumptions.
05 Management
Review ownership, legal structure and the operator's relevant experience. Identify staffing gaps and qualifications needed to carry out the project.
Sample report pages
Three pages from an illustrative study show how the finding, the five tests and the downside case appear in the report. The project and its figures are made up for this sample.
Engaged by the lender
The lender or Certified Development Company (CDC) engages Pinnacle Apex Partners directly. Any borrower payment of the study fee is handled through the lender or CDC under the written engagement terms.
The study includes an executive summary, the five tests, a conclusion and recommendation, and the preparer's qualifications and independence statement. A Reliance Letter names the Lender, CDC and SBA/USDA as applicable, and states the intended use and reliance limits.
Before work starts, we agree on the scope, required source documents and delivery date. We check for conflicts and accept only files in which we have no transaction interest. The lender and agency retain their credit and eligibility decisions; the study doesn't guarantee loan approval or acceptance.
Fixed fee, agreed before engagement
Fixed fee quoted in writing before engagement. Single-site SBA studies start at $5,000; special-purpose SBA 504, USDA B&I, conventional, and complex files are quoted by scope after file review. Never contingent on loan approval.
Service boundaries
Pinnacle Apex Partners, LLC is not a licensed CPA firm. It does not perform AICPA attestation engagements (including USDA Community Facilities examination opinions), compilation engagements, USPAP real estate appraisals, SBA Qualified Source business valuations, or Quality of Earnings reports.
Start with the lender's file requirements
Email the loan program, proposed site and use, financing amount, and your credit review date. We'll confirm fit and the documents needed for a written scope.
Brandon J. Jones, Managing Director
brandon@pinnacleapexpartners.com
404-445-6876